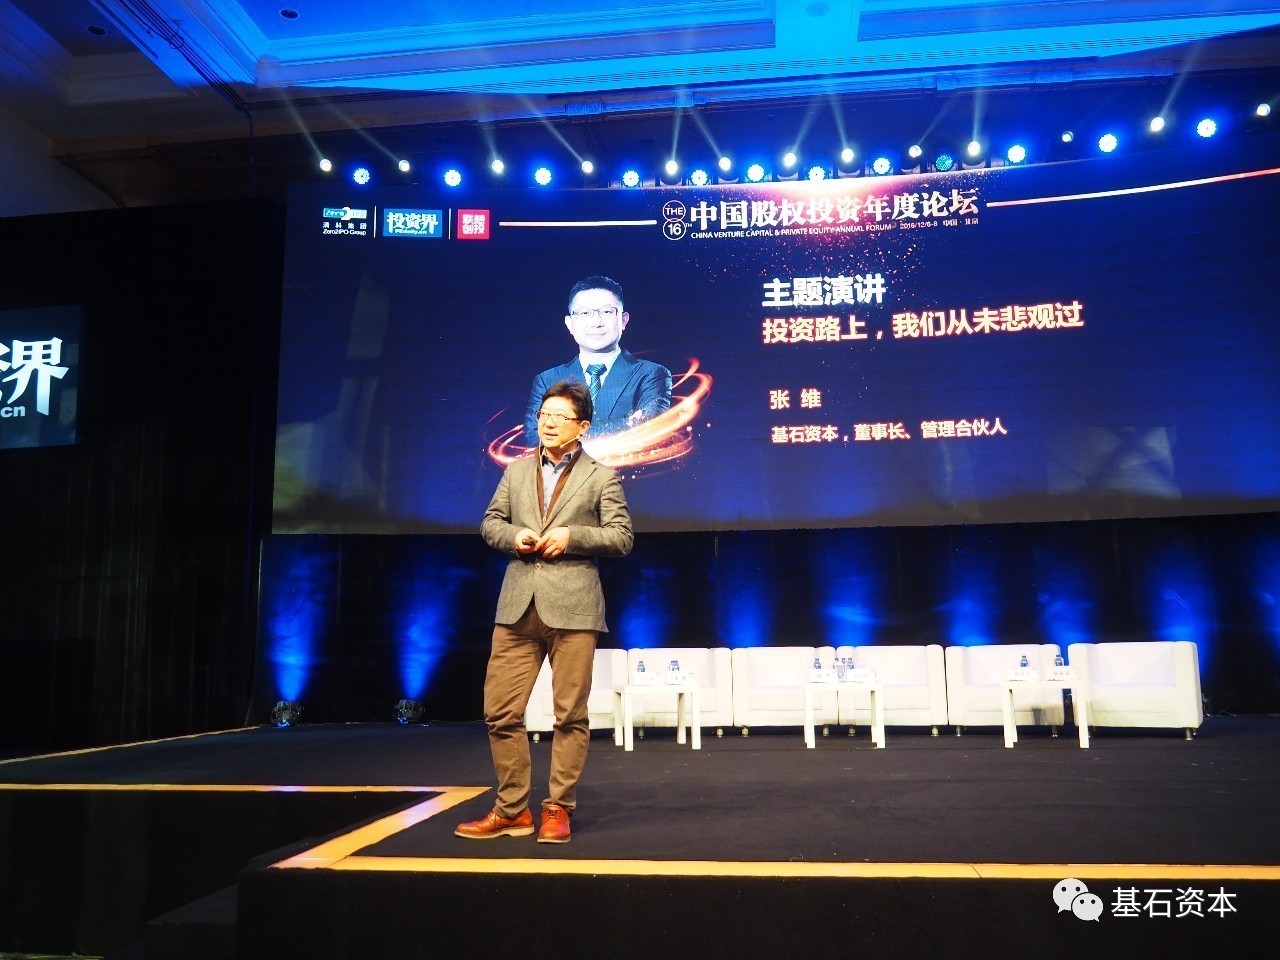
The 16th China PE Investment Annual Forum, co-hosted by Zero2IPO Group and PE Daily, opened in Beijing from December 6th to 8th in 2016. Over 3000 professionals participated in this Forum. The Forum was ended by the highly expected “Zero2IPO 2016 China PE Investment Annual Lists”: CoStone ranked the 8th on the 2016 Zero2IPO Top 100 China PEVC Institutional Investors; Zhang Wei, the CEO of CoStone was among the “2016 Top 10 Chinese PEVC Investors”.
READ
“We blazed a trail in TMT industries. We brought in professionals of telecom, chemical engineering, electronics and other emerging industries since 2012. Our effort finally paid off. CoStone was able to penetrate into the whole industrial chain and make arrangement for every stage within four years, instead of only touching upon the late-phased projects. The projects we invested in the last couple years fully embodied our style in TMT industry. These arrangements are different from what we do in the racing tracks. We have our own way. We will invest those projects that are promising and are related to capital markets and our core capabilities.”
READ
As Howard Marks stated in The Most Important Thing Illuminated: Uncommon Sense for the Thoughtful Investor, "first-level thinking is coming to a simple obvious conclusion and making a bet on it, while second-level thinking is deep, complex and convoluted and involves many factors." To obtain excellent investment results, one has to take an extraordinary but correct view towards value.
READ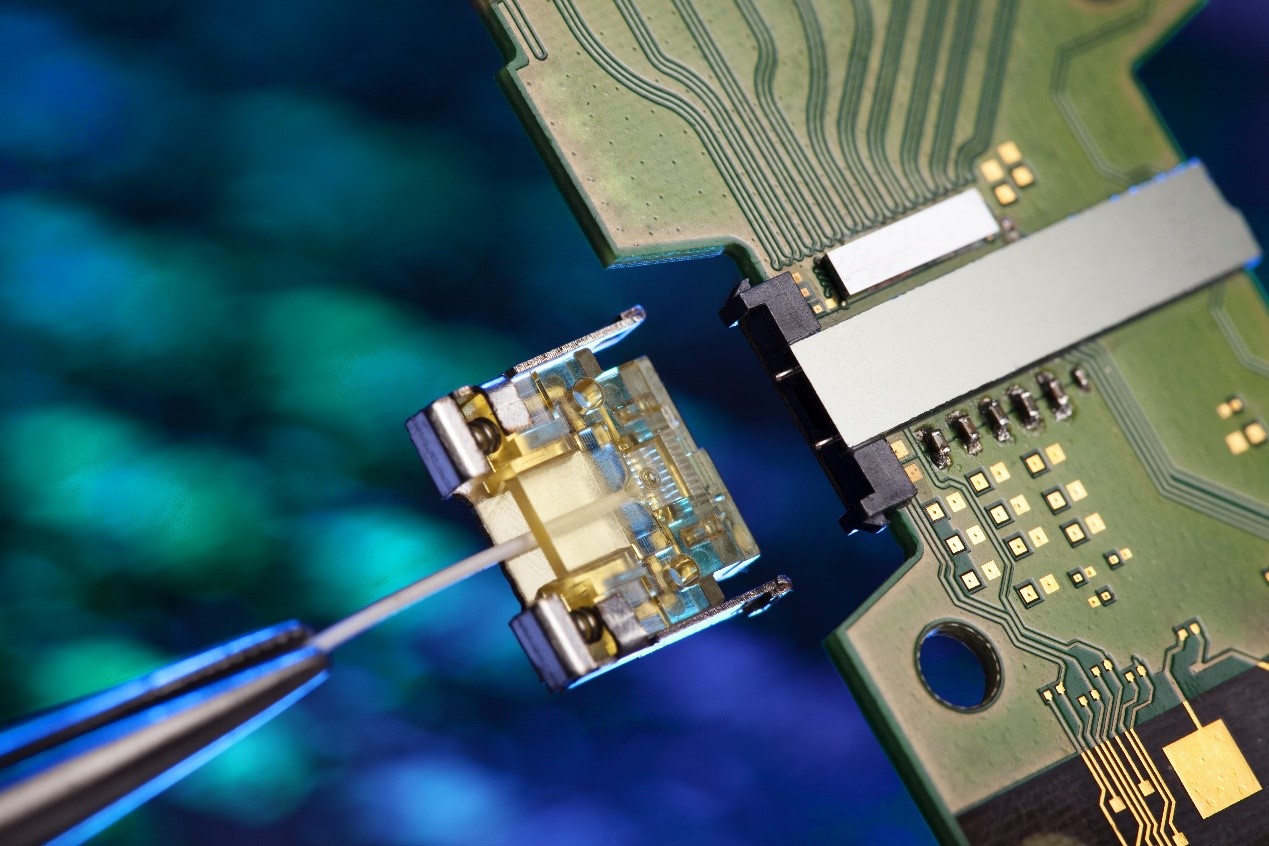
TMT has become the latest darling of investors over the past five years. It is helped by the fast-developed smartphone and mobile internet industries and the inclusion of O2O. The digitalization of traditional Chinese manufacturers and their new business models are also part of the reason.
READ
In the 2016 Chinese Venture Culture & Industry Capital Conference, two investment portfolios of CoStone won big prizes. MeWe Media was awarded as the best portfolio and acquisition of China’s M&E industry of the year 2015 to 2016 and Joyme was awarded as one of the ten most valuable new OTC market listed companies.
READ
CoStone Qomolangma Fund, an excellent PE investment fund since August 2011, has gained a complete victory in 19 projects across 3 fields with 1.4bn investment. Over 50% of its projects will go public, earning CoStone 5 times more than 75% of its original capital of investment.
READ
Lin Ling indicates that IP, originally referring to intellectual property, is now entitled to a sort of glory. IP may be another universe with another set of values. People in that universe live a different life which has well-designed plots. These plots incentivize the demands of consumers and fans. The loyalty of fans and consumers to IP makes it go viral. This mania can reduce the risk of investing similar projects.
READ
Long-term and continuous contacts will tell you the story about entrepreneurship which is featured by workaholism, persistence, and extraordinary business sense.
READ
“We will stay away from those who go against the trend. Never hold a piece of ice on your hands in a hot summer.” said Chen Yanli.
READ
Over the past year, the bull market returned, with technology leading the way.
As I said back in October 2024, the rally that began on September 24 was not merely a rebound, but a reversal. Since then, China's capital markets have undergone a broad revaluation, moving from undervaluation toward fair value.
The Shanghai Composite Index reached its highest level in a decade. The "Yi-Zhong-Tian" trio—Eoptolink, Zhongji Innolight and TFC Communication, three prominent Chinese optical communications stocks—saw their share prices multiply severalfold in a single year. Cambricon's market capitalization briefly exceeded RMB 600 billion. Elsewhere in the technology sector, triple-digit price-to-earnings ratios and valuations exceeding RMB 10 billion became commonplace.
Some investors were greedy; others, fearful. Still others asked me: Are technology stocks in a valuation bubble?
My answer is that what we are witnessing is the hunger and anxiety of an era, reflected in the capital markets. Once you understand this, the current fervor for technology investing is no longer difficult to explain.
Investment has nothing to do with macroeconomics, but everything to do with geopolitics.
China-US relations will shape the investment landscape for decades to come. Geopolitics has played a major role in shaping the hunger and anxiety of our times, fundamentally reshaping the way we invest.
What, then, lies at the heart of China's hunger and anxiety?
The Fourth Industrial Revolution is already underway, yet China has not fully overcome the technological shortcomings left by the Third. There is no time to lose.
This is why some people wonder: Why do Chinese computing chip companies command such high valuations when their technologies still lag so far behind NVIDIA's? Why does NVIDIA trade at just 50 times earnings, while a company hailed as "China's answer to NVIDIA" commands a multiple of 300?
To me, this gets the logic exactly backward.
It is precisely because these companies cannot catch up with NVIDIA in the near term that they command a higher strategic premium. The wider the technological gap, the greater the strategic value.
The further something lies beyond our reach, the stronger our hunger. The harder it is to catch up, the deeper our anxiety. If China were to achieve a complete breakthrough in computing chips one day, valuations might actually come down.
Where can one find China's most spectacular natural landscapes?
Much of the answer, I believe, lies in and around the Hengduan Mountains: the Meili Snow Mountains, Jade Dragon Snow Mountain, Mount Gongga, Mount Siguniang, Jiuzhaigou, and many others. Vast differences in elevation and deep fault lines have given rise to landscapes of extraordinary grandeur.
Hard-tech investing follows a similar logic.
Technological gaps, discontinuities in capabilities, and missing links in industrial systems: a leap in difficulty brings a leap in valuation, and a successful breakthrough can, in turn, bring a leap in returns.
This logic extends well beyond computing chips. It is equally evident in memory semiconductors, commercial spaceflight, and other sectors where China still faces substantial technological gaps with other countries.
It was precisely this conviction that led CoStone Capital, starting in 2016, to decisively focus its investments on three areas: hard tech, emerging industries, and life sciences and healthcare. In this context, "hard tech" refers specifically to important industries in which China faces a technological gap with the United States.
Thanks to this forward-looking strategy, CoStone Capital established an early presence across the full value chains of key sectors, including semiconductors, artificial intelligence, and robotics.
Looking ahead, the frontiers of technological progress and industrial upgrading are boundless. Nor can the gaps in hard technology be closed overnight. The twin windows of opportunity presented by technological innovation and the development of homegrown alternatives to foreign technologies have only just begun to open.
The road ahead is long, but the future holds immense promise.
As an investment firm, CoStone Capital will continue to invest where the hunger and anxiety of each era run deepest, move forward with the tensions that shape our times, and extend our reach toward the most challenging—and most important—frontiers.
Spring 2026